Sanchita
SanchitaFIRE
Dual-Phase FIRE Engine & Private Financial Memoir

FIRE Calculator & Retirement Planner

“Numbers calculate where you are going. Sanchita remembers how you got there.”

Model dual-phase retirement wealth with annual SIP step-up compounding and inflation-adjusted drawdown. Sanchita is also building a calm, local-first financial memory journal for mobile — 100% private, on-device, and offline.

Use the Free FIRE Planner
100% Private Client-Side Math
Annual Step-Up SIP Simulation
Mobile Journal App Coming Soon
Interactive FIRE Engine

Calculate Your Path to Financial Freedom

Model dual-phase retirement mathematics: annual step-up SIP compounding during your career, followed by inflation-adjusted monthly drawdown.

Simulation Assumptions

1. Age & Timeline

Current Age
Your age today
28 yrs
18 yrs75 yrs
Retirement Age
Target FIRE age
50 yrs
18 yrs85 yrs

2. Wealth Accumulation (Pre-Retirement)

Starting Net Worth / Corpus
Current invested savings
₹15.00 L
050,000,000
Monthly Investment (SIP)
Starting monthly contribution
₹50,000/mo
1,000500,000
Annual SIPStep-Up
Yearly contributionhike
10 %
0 %25 %
Expected Return
Pre-retirementgrowth
12 %
4 %20 %

3. Retirement Living & Inflation

Current Monthly Expenses
Living cost in today's money
₹60,000/mo
10,000500,000
InflationRate
Annual cost rise
6 %
2 %12 %
Post-Ret.Return
Conservativegrowth
7 %
3 %15 %
Life Expectancy Horizon
Planning duration
85 yrs
60 yrs100 yrs

4. Advanced Planning (Optional)

Add future milestones, retirement income, or an estimated tax-drag scenario.

Projection Summary
Withdrawal Rate: 1.67%

Sustainable Through Age 85+

Your portfolio sustains your inflation-adjusted lifestyle through age 85, leaving an estimated surplus of ₹95.36 Cr.

Projected Corpus at Age 50
₹15.53 Cr
Exact: ₹15,52,62,574
Monthly Living Cost at Retirement
₹2,16,212/ mo
Inflated at 6%/yr from today's ₹60,000
Total Invested₹4.43 Cr
Wealth Growth₹11.09 Cr
Annual Exp. at Ret.₹25.95 L
Personalized PDF · One-time purchase

FIRE Archetypes & Coast Status

Simulation-Derived Targets
Lean FIRE70% Living Cost
Required Corpus:₹5.07 Cr
₹42.0k/mo todayAge 85+
Active Plan
Regular FIRE100% (Primary Baseline)
Required Corpus:₹7.24 CrPlan Projects: ₹15.53 Cr
₹60.0k/mo todayAge 85+
Fat FIRE140% (Luxury Buffer)
Required Corpus:₹10.13 Cr
₹84.0k/mo todayAge 85+
Coast FIRE:In Progress

₹37.33 L more required today to reach Coast FIRE (assumes no future SIP contributions).

Coast Target Today₹52.33 LCurrent: ₹15.00 L

Corpus Trajectory &Longevity Curve

Accumulation with SIP Step-Up →Drawdown with InflationAdjustments

Pre-Retirement (Growth)
Post-Retirement (Drawdown)
Explore timeline to inspect balances & cashflows
₹0₹33.99 Cr₹67.98 Cr₹103.0 Cr304050607080Retire: Age 50
Explore across the timeline to inspect monthly corpus balance and cashflows.
22 Years Accumulating35 Years Drawdown
Milestone (₹1.00 Cr):Age 34.3(6.3 yrs away)
Wealth Doubling (₹2.00 Cr):Age 37.6(+3.3 yrs)

Need an archival copy of your retirement plan?

Generate your personalized multi-page FIRE dossier with complete archetypes, cashflows, and assumptions audit.

Personalized PDF · One-time purchase
MATHEMATICAL ARCHITECTURE

How the Sanchita FIRE Planner Works

Standard retirement calculators assume flat contributions. Sanchita models realistic compounding across accumulation, step-up hikes, and drawdown.

01

Build

Pre-Retirement

Your starting net worth and monthly SIP compound at your portfolio growth rate across your working years.

02

Step Up

Income Growth

Your monthly investment increases annually by your step-up rate, modeling real-world salary progression.

03

Adjust

Inflation Math

Today’s living expenses are compounded annually by inflation to calculate your true living cost at retirement.

04

Draw Down

Post-Retirement

Post-retirement, your corpus generates monthly returns while funding inflation-indexed monthly living expenses.

05

Test Longevity

Safe Horizon

The engine tests if your portfolio sustains through life expectancy or pinpoints the exact depletion age.

Subscribe to the Sanchita Journal

Financial memoirs & compounding math [Zero spam]

COMPREHENSIVE RETIREMENT GUIDE

The Definitive Guide to FIRE & Step-Up SIP Compounding in India

An authoritative reference on early retirement mathematics, safe withdrawal rates, inflation-adjusted drawdown, and sequence of returns risk.

1. The Four FIRE Archetypes

Financial Independence, Retire Early (FIRE) is not a one-size-fits-all milestone. Depending on lifestyle goals and discretionary spending, retirement journeys generally fall into four distinct categories:

Lean FIRE
Covers only essential, non-negotiable living expenses (housing, groceries, utilities, basic healthcare). Requires 20× to 25× annual expenses with minimal lifestyle padding.
Regular FIRE
Maintains your current comfortable lifestyle into retirement, including vacations, dining out, and family commitments. Requires 28× to 35× annual expenses.
Fat FIRE
Abundant, uncompromised financial freedom with substantial discretionary headroom for luxury travel, philanthropy, and premium healthcare. Requires 45× to 60× annual expenses.
Coast / Barista FIRE
Accumulating enough invested capital early so that compound growth will fund traditional retirement without further savings, allowing you to transition to lower-stress passion work.

2. The Step-Up Multiplier: Why Static Contributions Underestimate Wealth

Conventional retirement calculators model a flat, unchanging monthly contribution. In reality, human careers experience annual salary appraisals, bonuses, and expanding income capacity. Incorporating an annual Step-Up contribution (e.g., 5% to 10%) dramatically alters the compound wealth curve.

Scenario (20 Years @ 12% CAGR)Total Capital InvestedFinal Corpus AccumulatedWealth Multiplier
Flat ₹30,000 / month₹72 Lakhs₹2.99 Crores4.15×
10% Annual Step-Up SIP (Starts ₹30k)₹2.06 Crores₹6.23 Crores2.08× More Wealth

*Table assumes 12% annualized equity returns compounded monthly over 240 months with 10% annual Step-Up increments.

3. Post-Retirement Inflation & Sequence of Returns Risk

The greatest threat to long-term retirement longevity is not market volatility during wealth accumulation, but Sequence of Returns Risk (SRR) combined with relentless inflation during the drawdown phase.

The Inflation Compounding Reality in India (6% Annual Rate):

  • Current Living Expenses: ₹50,000 / month (Age 28)
  • Expense at Retirement (Age 50): ₹1,80,175 / month (3.6× increase)
  • Expense in Late Retirement (Age 75): ₹7,73,300 / month (15.4× increase)

If your retirement corpus experiences negative market returns in the first 3 to 5 years while you withdraw inflation-adjusted sums, capital depletion accelerates irreversibly. Sanchita explicitly simulates this monthly balance degradation to ensure your portfolio sustains through life expectancy.

4. Safe Withdrawal Rates: Trinity Study (4%) vs. India (2.75%–3.25%)

The popular "4% Rule" originated from the 1998 US Trinity Study, which tested 30-year retirement horizons in a 2%–3% inflation environment. Applying a static 4% rule in developing economies like India with 6%–7% long-term inflation and 35+ year early retirement horizons carries a high failure rate.

Traditional 30-Yr Horizon3.5% – 4.0%2.5% Inflation / 30 Years
Recommended Indian FIRE2.75% – 3.25%6% Inflation / 35-45 Years
Ultra-Safe Horizon2.25% – 2.50%Generational Wealth Transfer

5. Mathematical Framework & Simulation Engine Formulas

A. Annual Step-Up Monthly Recurrence (Accumulation Phase):C(m) = C(m - 1) × (1 + r_m) + P_mWhere r_m = (1 + r_pre)^(1/12) - 1, and P_m steps up by (1 + s) every 12 months.
B. Post-Retirement Inflation Drawdown Recurrence:C(m) = C(m - 1) × (1 + r_post_m) - E_mWhere monthly living expense E_m compounds annually by (1 + inflation_rate).
C. Real Rate of Return (Fisher Equation):r_real = (1 + r_nominal) / (1 + inflation) - 1Calculates the authentic purchasing power growth of the portfolio net of currency debasement.
सं
THE SANCHITA PHILOSOPHY

Money is not simply a ledger of numbers.
It is the evolving story of your life.

FIRE calculators project where you are heading thirty years from now. Sanchita preserves the life chapters, relationships, and moments behind where you are today.

Because a career transition isn’t just a line item on a spreadsheet, and an anniversary dinner isn’t just a line in a deficit category.

Conventional Expense AppsSpreadsheet Anxiety & Guilt
  • Ledger-first: Clinical double-entry balancing and red deficit warnings.
  • Generic labels: Meaningful life memories collapsed into sterile categories.
  • Gamification: Daily streaks, push notifications, and spreadsheet fatigue.
  • Cloud tracking: Mandatory remote sync and financial telemetry.
Sanchita MemoirCalm, Archival & Local-First
  • Memory over ledger: Qualitative reflections are primary; numbers are context.
  • Life themes: Grouped into Routine, Relationships, Exploration, and Milestones.
  • Quiet experience: Zero streaks, zero push notifications, zero judgment.
  • 100% Local-first: Stored strictly on your device with complete JSON export.

“Five years from now, you won't remember what you spent on July 14th. You will remember the bakery where you sat while planning your career transition.”

Mobile Journal Preview

Sanchita is Coming to Mobile

A quiet, private personal archive on your phone. Built with 100% local-first storage, calm typography, and zero tracking.

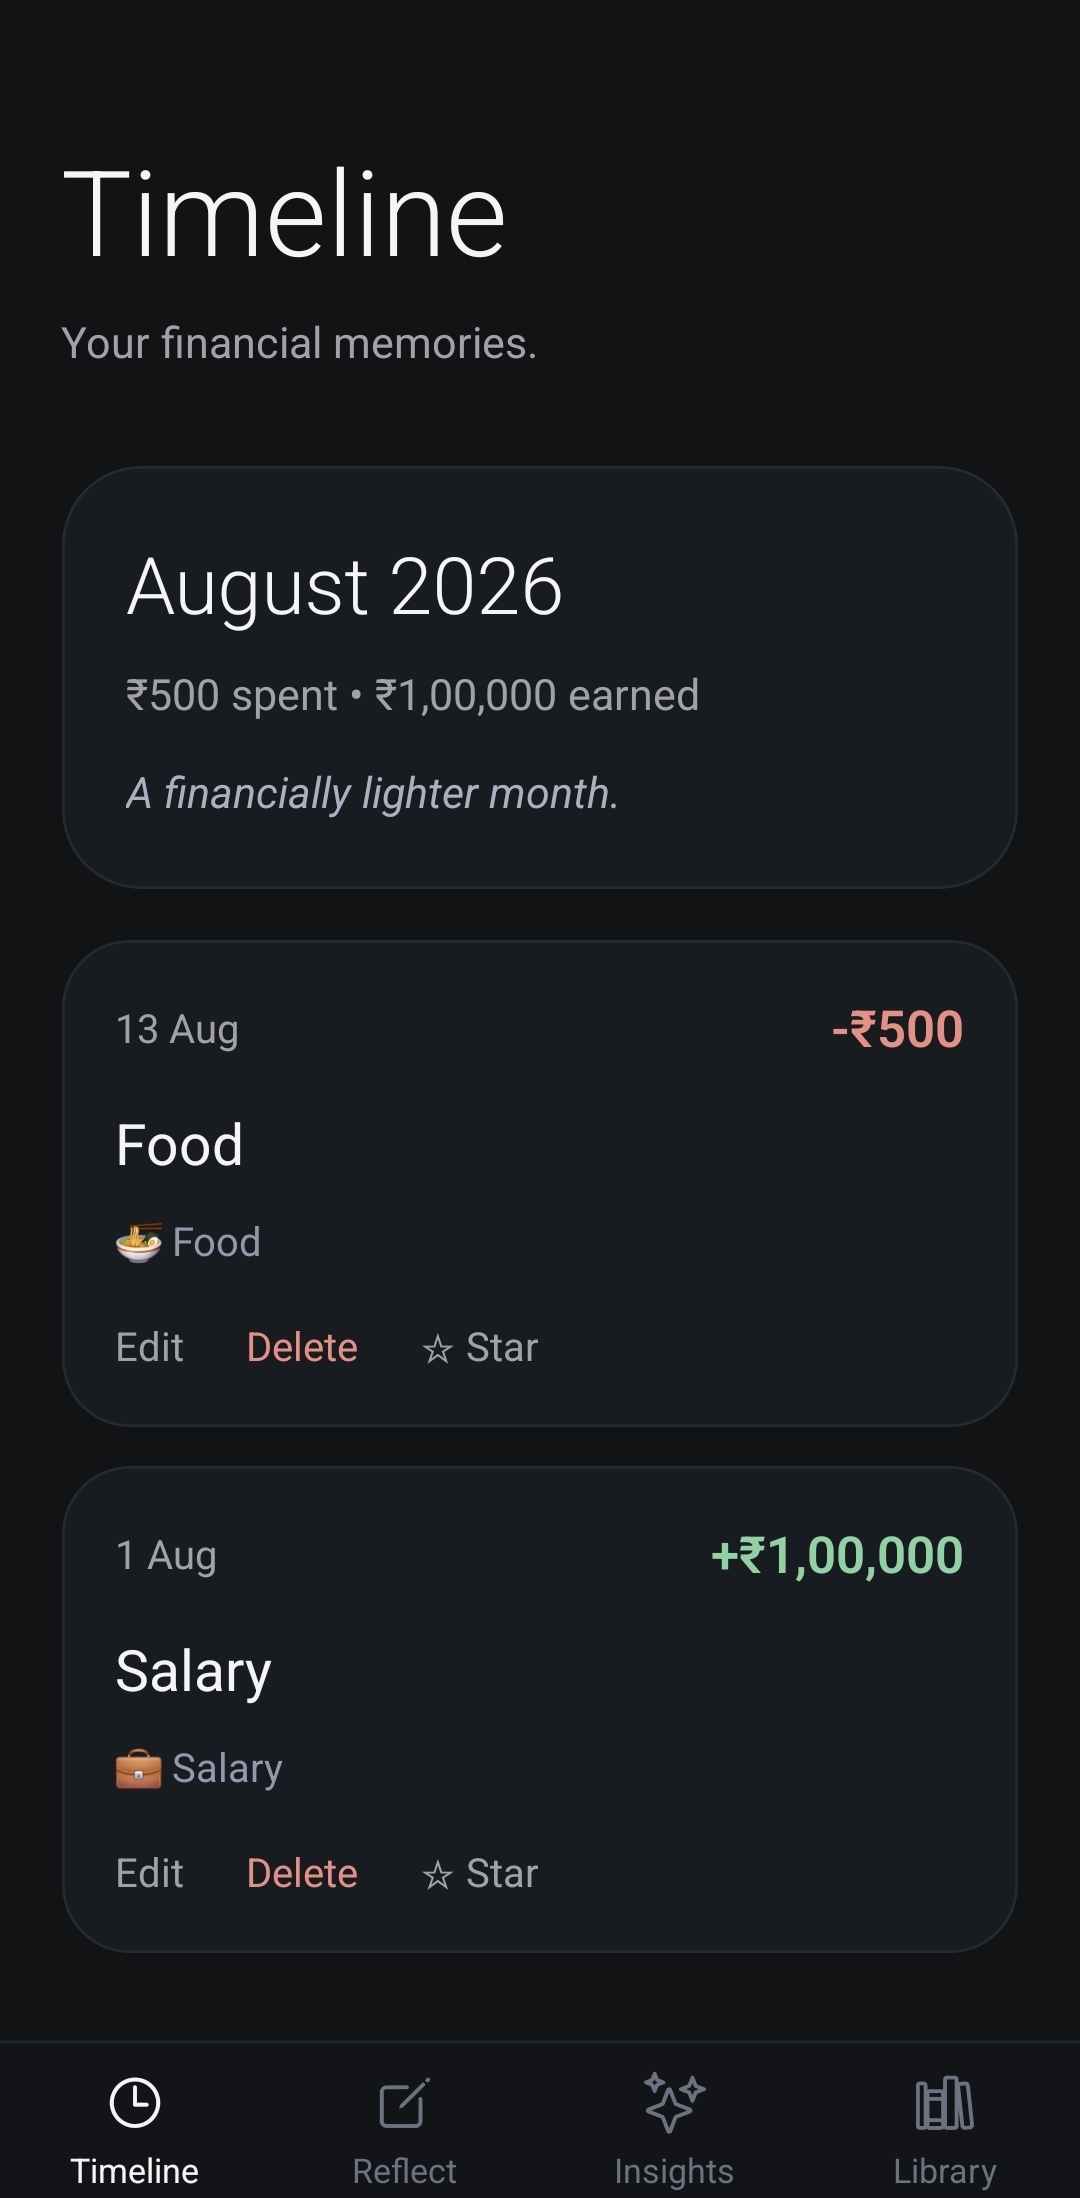
Timeline

Shallow, Human Chronology

Current month is gently expanded with memory notes; older history is preserved without endless scroll fatigue.

Reflect

Mindful Journaling Entry

Insights

Annual Life Retrospectives

Library

Archival Memory & Local Control
Sanchita mobile app timeline screen showing financial memories and monthly reflections
Timeline Screen
Local-First Guarantee

Your Life Memoir Belongs Solely to You

Financial journals contain your most vulnerable life moments. Sanchita is architected so we never see, store, or sell a single entry.

100% On-Device Local Storage

Every reflection, amount, star, and life note is written directly to your device’s local filesystem. There is no remote central database, no sync server, and no cloud ledger holding your personal financial history.

Zero network transmission for your entries

Zero Financial Data Harvesting

We never collect or profile your net worth, expenses, or life notes. Calculator inputs and financial projections run 100% client-side in your browser and are never transmitted.

Private client-side computation • No personal profiling

No Bank Credential Scraping

Sanchita avoids aggressive bank account linking and SMS permission scraping. Journaling is an intentional, mindful act of self-awareness rather than passive automation.

Deterministic & 100% Offline Core

All calculations and journaling flows run completely offline. No AI hallucination, no cloud outage vulnerabilities, and zero mandatory subscription paywalls for your records.

Open Data Ownership: Export your complete journal archive anytime as a standard JSON file. You are never locked in.
Open Format • Self-Custody
Frequently Asked Questions

Retirement Mathematics & Sanchita

A FIRE (Financial Independence, Retire Early) calculator models how much capital you need to accumulate to sustain your living expenses without relying on active employment. Unlike basic savings tools, Sanchita models both the pre-retirement wealth accumulation phase and post-retirement monthly drawdown.
AUTHOR & ENGINEERING GOVERNANCE

About the Creator & Engine Architecture

Sanchita is an independent, engineer-led project dedicated to deterministic mathematical modeling, financial clarity, and uncompromising user privacy.

AB

Abir Bandyopadhyay

Creator & Lead Engineer

Software engineer & creator of Sanchita, focused on deterministic algorithms, financial modeling, and local-first privacy.

Deterministic Math

Discrete monthly compounding with exact geometric step-up annuities and inflation-indexed drawdown formulas.

Zero-Telemetry Privacy

100% of calculations execute locally in browser RAM. Your salary, expenses, and portfolio numbers never touch a server.

Unbiased & Independent

Free of corporate financial advisory biases, distributor commissions, or hidden affiliate fund rankings.